Rocketing Defense Spending’s Effect on Middle-Market M&A
Merit Investment Bank’s Chris Abato and Leonid Capital Partners’ James Parker join the podcast
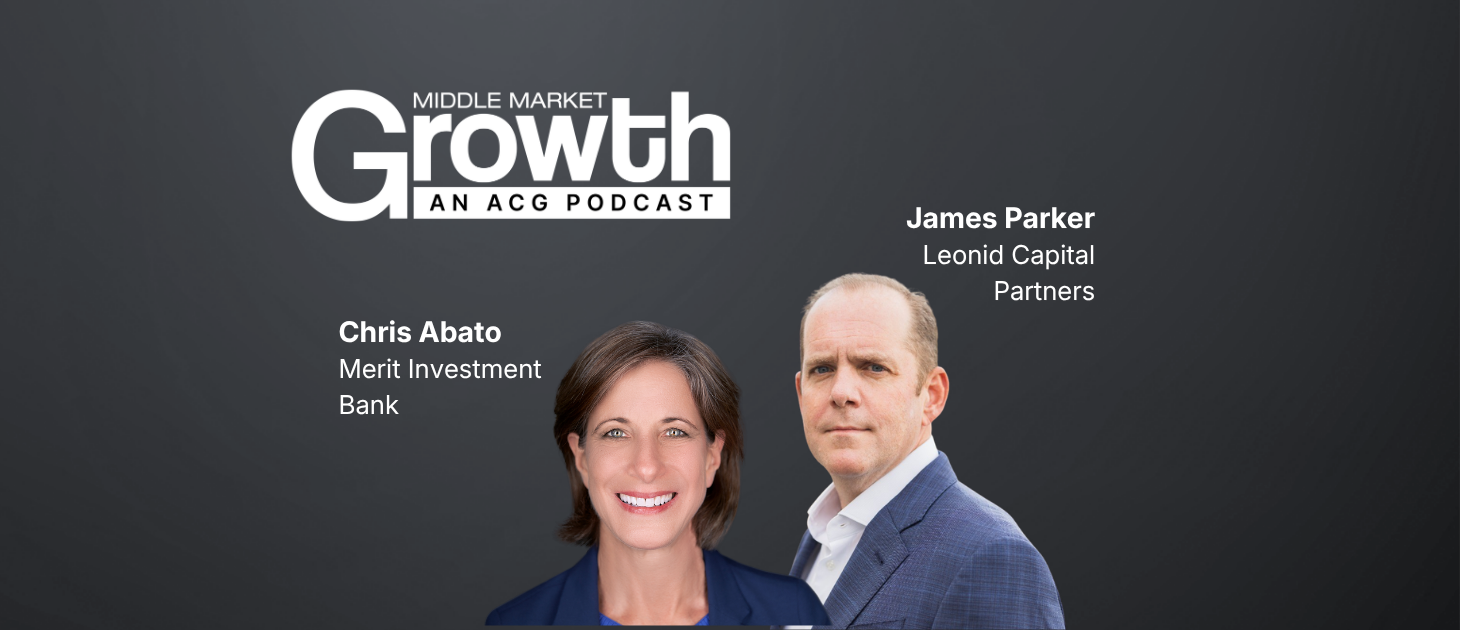
Rising geopolitical conflict and projected record defense spending signal a potential wave of middle-market deals for companies in the aerospace and defense sector. Merit Investment Bank’s Chris Abato and Leonid Capital Partners’ James Parker join the podcast to discuss trends in defense sector dealmaking, the health of the A&D supply chain, and what considerations dealmakers should keep in mind as they scour the sector for targets.
This episode is brought to you by Grata. Learn more at grata.com.
Read a transcript of the podcast below.
Middle Market Growth: Welcome to ACG’s Middle Market Growth. I’m Carolyn Vallejo. Against the backdrop of rising geopolitical conflict and record defense budgets, defense dealmaking could be headed for a new heyday. It will be one of several major A&D trends highlighted at ACG’s upcoming A&D Middle Market Leadership Forum. Joining us today are two of the forum’s panelists, Chris Abato of Merit Investment Bank and James Parker of Leonid Capital Partners. They’re here to discuss the effect of this massive spending on middle-market M&A, as well as the outlook for the broader A&D sector. Chris and James, welcome to the podcast.
Chris Abato: Thank you.
James Parker: Thanks for having us.
MMG: First, let’s start with you, Chris. Could you tell us a little bit about your role at Merit and what you focus on there?
CA: Yes, happy to, and thank you for having us. I’m Chris Abato, a managing director at Merit Investment Bank. We’re a boutique investment bank focused on middle-market transactions, primarily sell-side deals ranging from $20 million to $200 million. I lead the aerospace and defense sector, having spent 22 years at Lockheed Martin focused on buy-side deals. I also focus on technology deals, since I’m in the middle of Silicon Valley. I have a physics degree, so I love to geek out on technology.
MMG: And James, what about you?
JP: I’m the founding partner at Leonid Capital Partners. We’re a private credit firm focused exclusively on the national security and intelligence community sectors. We’ve been around for about seven years and have completed more than $600 million in deals in this space through a fairly novel private credit approach. We currently have offices in Huntington Beach and Washington, D.C.
MMG: And just for a little bit of fun, we ask all our guests this: If you had to choose a walk-up song, what would it be? James, let’s start with you.
JP: Unfortunately, I’m a child of ’90s hip-hop, so anything I would answer here would be wholly inappropriate, much less unprofessional. I’m going to decline to answer.
MMG: Fair enough. Chris, what about you?
CA: I love opera, but last week I was having a really stressful week. I go on a four-mile hike every evening, and I put on the Mamma Mia! soundtrack. It cut a minute off my pace for each mile. So I’m going to go with “Mamma Mia.”
MMG: I like the range we have going between the two of you. That is great.
CA: Exactly.
MMG: Getting into our main topic today, we’re taking a look at middle-market M&A in the defense sector. I’d like to start by setting the scene and discussing some of the major trends shaping the space right now. Chris, why don’t you kick us off?
CA: Sure. We’re seeing four major trends in the aerospace and defense sector. First is the significant increase in defense spending. Global defense spending is projected to exceed $3 trillion by the end of this year. That’s a 26% increase over the last three years. NATO allies have committed to spending 5% of their GDP annually by 2035, and U.S. defense spending is up 11% from last year. Second is increased demand for production. This is driven by the fact that we have two wars underway and have significantly depleted our stockpiles. For instance, if the United States fired 1,000 Tomahawk missiles, it would take until 2030, at current production levels, to replenish them. The same is true for THAAD and Patriot interceptors. We’ve depleted more than 50% of our stockpile. On the commercial aviation side, Airbus’ backlog reached more than 9,000 aircraft as of May this year. Production capacity and constraints can’t change overnight, so that’s an important area being addressed right now. The third trend is the focus on a new type of warfare: asymmetric warfare using next-generation technologies. That’s being driven by what’s happening in Ukraine with drones and autonomous vehicles combined with AI. An individual drone can cost about $1,000, while it may take a $4 million interceptor to destroy it. Those economics have to change. The fourth trend is the incredible increase in capital being invested in A&D, and I think James can discuss that in much greater detail than I can.
JP: I appreciate that, Chris. There has been an unprecedented rise in interest in the space, certainly on the early-stage side. A lot of that is driven by the projected increase in the U.S. defense budget, potentially to $1.5 trillion. The lion’s share of that increase is slated to go toward new and novel, nontraditional players. All of a sudden, you’re seeing an interesting demand signal from the government saying, “We’re looking for more novel applications of the latest, next-generation technology.” We know the Chinese are investing well ahead in these markets, and they don’t have the same constraints we have regarding procurement cycles, budget oversight, and democracy. We have an interesting pacing threat that we have to meet, and you’re seeing capital recognize that opportunity and come in. The question is how persistent that will be. One thing I’ve said in the past is that capital views the government as a trustworthy partner, but not necessarily a reliable one. There’s an interesting gap. When people are thinking in terms of seven- and 10-year fund horizons, how does that work when the defense budget is still appropriated year by year?
MMG: That’s a great point. You mentioned this massive defense budget, as well as significant innovation and unprecedented interest in the space. I want to get further into that because I know you’re both presenting on a panel called “Navigating the Defense Deal Surge” at ACG’s upcoming A&D Forum in October. Could you give us a sneak peek of what you’ll cover during that session? James, let’s start with you.
JP: The interesting thing is that defense deals naturally get grouped under one umbrella, when there are really a multitude of submarkets at play. You have PE roll-ups happening in specialized manufacturing. You have PE roll-ups in specialized service providers, ranging from IT providers to companies with particular capabilities. People see an opportunity to buy a platform and execute a traditional PE roll-up strategy. On the VC side, it’s a completely different story. You have companies with some, or perhaps little to no, government revenue commanding hundreds of millions of dollars in valuation and attracting significant capital. How those two markets develop is very different, particularly in terms of how they affect future M&A. Traditional PE doesn’t really deviate from its metrics. You’ll see those roll-ups happen consistently, but they’ll be confined to a particular subset of the market. The real question is what happens when some of these sky-high valuations on the VC side come home to roost. When it comes to ultimate transactions, IPOs, or M&A involving primes that have to focus on accretive transactions, the outcome remains to be seen.
MMG: Chris, what about you? Can you give us a sneak peek of the panel?
CA: Certainly. As James discussed, the U.S. appropriations process and our annual system for allocating money aren’t moving at the speed needed for us to gain traction with changes in warfare. What’s helpful is that the United States remains the largest defense spender, at about $1 trillion, and that is slated to increase another 50% next year. But, as James mentioned, China isn’t constrained by our democratic process. China and Russia combined are focused on more than $500 billion of investment, and they can direct that money wherever they want. One of the major concerns right now is freedom of the seas, land, and air, as well as freedom in space. We’re going to see a significant shift in space. Part of that was glamorized by Elon Musk and Jeff Bezos competing, but it’s much more than that. A lot of new companies are receiving investments at high valuations, and some may not even have a product yet, despite having $400 million or $500 million of investment. This is similar to the early 20th century, when there were roughly 400 automotive manufacturers in 1910. Twenty years later, only about 10% remained, and three had 90% of the market share. There are going to be winners and losers. A great deal of money is going into space, but space is a difficult environment. There will be consolidation, and some companies simply won’t make it. We’re at a fascinating point right now.
MMG: Absolutely. “Fascinating” was certainly the word that came to mind for me. We’re hearing glamorous headlines about space, significant innovation, and a huge budget. But, as you both alluded to, there are challenges in this industry as well. Chris, how are the challenges you’re seeing emerge in the industry starting to affect M&A? What are some of the headwinds?
CA: Supply chain capacity is a huge challenge right now. Part of that is replenishing our stockpiles, and part of it is simply that capacity takes time. It takes time to build a facility and bring in a workforce that can produce what is needed. The aging workforce is another challenge. Thirty percent of the aerospace and defense workforce is over 55. Fortunately, people are working longer because we enjoy working, but we still need a talented workforce that doesn’t just come out of excellent schools, but also has experience. There are other challenges, including sole-source supplier risk. When I was at Lockheed Martin, we worried that in some cases there was only one supplier. If a competitor bought that supplier, you were out. It’s a real vulnerability, particularly from a national security perspective. There’s also competition for raw materials amid the growth of data centers and other industries. Titanium, aluminum, and copper are under pressure, and the tariff dispute with China is adding more pressure. Then there’s the rigidity of our defense budget, the appropriations process, and continuing resolutions. The old procurement model isn’t keeping up with the speed of conflict and how quickly we need to respond. Those are significant challenges.
JP: The aging workforce in aerospace and defense was a problem 20 years ago when I was an engineer at Lockheed and Raytheon, so I think that concern may be somewhat overblown. Opportunity tends to find its level. But I don’t disagree that we have headwinds. When it comes to attracting all this additional investment, that investment ultimately has to produce a return at some of these valuations. That becomes an issue because you’re putting many companies into an IPO-or-bust category. The only legitimate acquirers for some of these single-product, novel defense technologies are the primes. The primes can’t do deals unless they’re accretive. It simply won’t work with their capital structures and public-market expectations. I love the mission at Castelion, and I think there’s a market for that product, but the company is valued at approximately $13 billion, while Lockheed Martin is worth about $130 billion. If a venture investment has to return at least 10 times, and generally needs a path toward 100 times for fund-level VC math to work, do we really think Castelion will be worth an entire Lockheed Martin, let alone 10 of them? I don’t know. How does that exit happen? I’m not saying it can’t. The world has a habit of changing, and betting against technology is generally a poor thesis. But it’s structurally difficult. You can’t force market multiples to change. I’m concerned that we’re setting people up for the inevitable VC letdown. That’s why venture in the defense space has always made me uneasy. People enter these investments believing it’s the best technology and that it will protect the warfighter and our interests. But venture math works in a particular way. If you have a down cycle, you’re out, because venture fund returns don’t work when holding companies that aren’t growing or are losing money. How do you reconcile the view that this is critical technology that will drive the country’s strategic defense advantage with the reality that one bad quarter can cause investors to abandon it and put their money into a winner? That’s why I like our credit approach. It allows me to back almost everybody as a winner instead of trying to pick one winner from an existing portfolio.
CA: Something like 26 new space startups have raised more than $5 billion recently. To your point, James, I don’t know where this can go.
JP: Unfortunately, Chris, you’re barking up the wrong tree with me. I’m extremely bullish on space. That’s the one side of the market where I would continue to invest regardless of valuation. A lot of that has to do with my background. I’m a giant space nerd and couldn’t believe more strongly in the prospects for both the commercial and national security sides of the space market. But you’re not wrong. Skepticism is wise in this market.
MMG: Another challenge you mentioned at the top, Chris, was the supply chain. That’s one of the topics ACG is covering in its A&D report, which will be released later this month. We’ve discussed talent challenges, the inability to meet demand, and the backlog you both mentioned. How resilient or fragile is the defense-sector supply chain today?
CA: Some of the challenges involve tier-two, tier-three, and tier-four suppliers, where there may be a single-source supplier or perhaps only one-and-a-half viable sources. Part of the problem is the time required to qualify a supplier to perform on these contracts. Access to raw materials is also making products difficult to build, and there’s competition for those materials even within the United States. Microelectronics are highly concentrated. Something like 90% of microelectronics production and 98% of assembly, packaging, and testing occur overseas, primarily in Taiwan, South Korea, and China. That’s eye-opening. Production facilities also can’t scale quickly enough to replenish stockpiles. On the resilience side, the market does adapt to what is needed. Production capacity is expanding because there’s significant focus and investment. There’s also investment in supply diversification and strategic reserves. The primes are maintaining always-on production, which helps keep capacity running at a certain level. Broader industrial participation, including dual-use production, helps maintain production levels because companies serve both commercial and defense customers. We’re seeing greater investment and engagement with startups and nontraditional defense suppliers. As long as there isn’t an ITAR constraint, dual-use companies can serve a commercial market with steady demand while also being available when defense demand surges.
MMG: James, what are your thoughts on the resilience versus fragility of the defense supply chain?
JP: This is a bigger issue that goes deeper than defense. Consider a striking example: It can be cheaper to buy finished aluminum goods from China than to buy the raw materials needed to produce them in the United States. Think about that cost advantage and how difficult it is, in a competitive environment, to consciously accept a significant cost increase to manufacture domestically. That also affects the dual-use thesis. If I’m trying to pursue a commercial strategy, how can I compete while maintaining a resilient supply chain and ignoring the obvious cost advantages of offshoring work that my competitors are probably offshoring? This goes much deeper. We need to broaden our understanding of what’s strategically important and what constitutes a national security need. We don’t make ibuprofen in this country. The precursors for antibiotics come from China. Imagine entering a shooting war with China and suddenly being unable to make antibiotics. We’ve put ourselves in an untenable position. I’m a capitalist, and I support globalization, but we have to recognize that some groups don’t share our values. It isn’t a sound national strategy to place critical parts of our society in the hands of people who don’t have our best interests at heart.
MMG: I imagine others share that opinion. I also want to return to the talent shortage and some of the workforce challenges we’re hearing about. You both mentioned, and had differing opinions about, how serious the aging-workforce challenge may be. James, are you hearing these concerns, and is this a concern for you?
JP: We’re intensely focused on the earlier-stage segment. We’re seeing an interesting shift. If you look at the demographics of founders in the space, the average space founder may be in the mid-30s, which is a byproduct of when SpaceX entered the national consciousness. Now you’re seeing the Palmer Luckey effect in defense technology, with 25-year-olds focusing primarily on the sector. It has become more acceptable on college campuses to work with the Pentagon on national security programs. We have these moments and driving personalities, and people like to emulate their heroes. People see that and enter those areas. Personally, I’m not nearly as bearish on the labor-shortage idea. That doesn’t address manufacturing, but I think manufacturing presents a deeper challenge than a labor shortage. When it takes two-and-a-half years to make a cruise missile because of how it’s constructed, you have a process problem, not simply a labor shortage.
MMG: Interesting. Chris, what are your thoughts?
CA: Technology evolves in response to need. We need different munitions, response technologies, and ways of building products so we can be more efficient as a nation and respond to demand. On the labor side, I see the value of experience. At Lockheed Martin, we worried that we would recruit brilliant engineers who would leave after five years to work for startups. That was during the dot-com era. The encouraging thing now is that there are many startups in aerospace and defense. If engineers make that shift now, it can make the entire industry stronger, more innovative, and more resilient. Many things are changing, including the efficiencies created by AI. We’re at an interesting point, and we have to be thoughtful about training the next generation while allowing that generation to move at its own speed in terms of innovation and ideas. We need a bilateral relationship between experienced and younger workers to solve our greatest problems.
MMG: I can’t believe we made it this far into the podcast without mentioning AI. Let’s return to some of the exciting and optimistic aspects of A&D and speak directly to dealmakers. What characteristics make a defense company attractive to an acquirer today? Chris, let’s start with you.
CA: We’re seeing a significant rebound in global aerospace and defense M&A activity. Annual deal value rose to just under $40 billion in 2025, up 61% from $24 billion in 2024. The number of transactions increased 33% to 465. In the second quarter of 2026, deal value doubled to almost $13 billion from $6 billion in the same quarter a year earlier. We’re seeing a great deal of M&A activity, but we’re not seeing excessive hubris. Acquirers are looking for accretive deals. Valuations are being driven by earnings, not just revenue or backlog. We’re seeing discipline even as values rise. We’re not seeing irrational valuations driven by desperation. Thoughtful, accretive transactions will be productive. Defense primes and large companies can’t innovate quickly enough through internal R&D budgets to respond to changing threats. They have to acquire proven technology and integrate it into their platforms more efficiently. On the government side, we’re seeing innovative proposal mechanisms that bypass the old, slow procurement model involving years of RFPs. We’re seeing unsolicited proposals and more SBIR investment to enable faster, more innovative responses. It’s an incredible time for M&A in aerospace and defense.
MMG: James, what are acquirers seeking, and what makes a target attractive in this space?
JP: Novel technology that helps internal R&D teams advance is critical. At the same time, an acquirer has to see a real path to additional contract dollars or a different color of money. Historically, primes acquired companies that opened access to new budget dollars or companies whose products competed with legacy systems, allowing the prime to maintain control of those budget dollars. Unfortunately, that’s often the tail that wags the dog. If you’re not meeting a big-R requirement, it’s a guess, and it’s difficult for corporate development teams at the primes to bet money on a guess. On the early-stage side, there’s significant focus on exits to SpaceX or Anduril because those companies aren’t operating under exactly the same paradigm. I’m not sure that will last forever. Ultimately, you have to abide by the rules of the game, which currently means the federal budget cycle. That can change, which makes the space interesting and resilient, but it has to be considered. It’s difficult for a team to take a flyer on new technology if it can’t see how to charge the government for it quickly. The technology needs to be beyond a certain TRL, meet a big-R requirement, and already be in the cycle for buyers to pursue it seriously.
MMG: We’ve talked about how quickly innovation and warfare are changing. Chris, where do you think the sector will be a year from now? What do you expect to change?
CA: U.S. spending will increase because we need to respond to emerging threats. Right now, we’re targeting $1.5 trillion next year, which would be a 44% increase over 2026. That budget includes $300 billion for R&D to support new platforms, weapons, and advanced technologies. I think that’s the right focus and an exciting opportunity. We’re seeing autonomous vehicles and drones move toward scale. I wrote a thought leadership paper about the convergence of autonomous technologies and how it’s changing the battlefield. Technologies from different applications have converged to make drones, autonomous vehicles, and counter-drone technologies much more effective. We’ll see real change there. Industrial capacity will increase, and younger and older workers will collaborate more effectively. Allied defense spending is another major change. European defense spending rose 14% in 2025 to almost $900 billion. We’ll see more collaboration with allies, more cross-border technology transactions, and more foreign companies establishing U.S. entities to respond to U.S. demand. We’re seeing a lot of change, and the next year will be very exciting.
MMG: James, how about you?
JP: Aside from my overall bullishness on the space market, which I expect to continue, I agree with Chris’ last point. Because we can’t achieve meaningful acquisition reform at the speed of technology, I think you’ll increasingly see companies go abroad to field their technologies as proof points and drive domestic orders. That’s unfortunate, but you’re already seeing it with companies taking technology to Ukraine. There is now official doctrine encouraging companies to contact the CTO at CENTCOM. A system might not be usable in INDOPACOM yet, but it can be tested in Africa, which is a useful sandbox and a representative sample of challenges we may face in the future. You’ll see more of that as a way to prove effectiveness instead of running the gauntlet of Army demand signals, heavy-lift challenges, and other processes that don’t move procurement quickly enough to justify incoming investment or meet the country’s strategic needs. We’ll see more questions about how technology is being used elsewhere. Poland will pay cash for technology, and it won’t require companies to run through the TRL cycle if it believes the technology will help deter Russia.
MMG: We’ve had a wide-ranging conversation. A&D is prolific and exciting, with a lot happening and significant change underway. To bring it all home, what is the biggest consideration dealmakers should keep in mind as they navigate the space? James, why don’t you start?
JP: No matter what you want to think, you’re always operating in the government’s market. That isn’t earth-shattering. This market will ultimately be driven by the bedrock of the American defense economy: the defense budget. The trends look good, but it isn’t multiyear money. Serious changes are needed. People should focus on a consolidated effort to drive those changes through the Pentagon and Congress instead of hoping that executive orders or memoranda will solve everything. The system needs fundamental change. If we’re going to fight an adversary that doesn’t face the same constraints, we can’t do so with one hand tied behind our back.
CA: I agree. We have adversaries that don’t play by the rules. Even though everyone may appear to stay in their corner, they don’t. Other countries are gearing up. A few months ago, Russia moved a satellite close to a Ukrainian satellite simply to demonstrate that it could. It didn’t damage the satellite, but it could have eavesdropped or taken it out. Dynamics are changing, and we can’t operate on the assumption that everyone will behave. There are many complex, unsolved problems. We need to consider how to solve them with new technologies and COTS solutions in a cost-efficient way. We have to work backward from the problem and ask what we need to do to preserve freedom of movement on land and in space so no one can deny us access. We have to take this seriously. Russia invaded Ukraine. That’s a very big deal. If Russia could get away with invading more territory, or if China could do the same, the consequences would be significant. Major powers may be staying put right now, but we shouldn’t count on that in the future. We have to be aggressive about protecting this country and our allies so bad actors can’t constrain us.
MMG: All right. That was a fantastic conversation with Chris Abato of Merit Investment Bank and James Parker of Leonid Capital Partners. Thank you both so much for joining us today.
JP: Thanks for having us.
CA: Fascinating topic.
MMG: Absolutely. For our listeners, don’t miss your chance to hear from Chris and James in person at ACG’s A&D Middle Market Leadership Forum on October 14 and 15 in Los Angeles. Register at acg.org/ad26. Before the event, catch up on more of the industry’s latest trends in ACG’s upcoming A&D report, out September 28 on acginsights.org.
This transcript was prepared by a transcription service. This version may not be in its final form and may be updated.
The Middle Market Growth podcast is produced by the Association for Corporate Growth. To hear more interviews with middle-market influencers, subscribe on Apple Podcasts, Spotify or Soundcloud.