ACG’s A&D Forum Unpacks the Sector’s M&A Trajectory
ACG’s recent Aerospace & Defense Middle Market Leadership Forum unpacked the sector’s active 2026 while considering how A&D dealmakers can brace for more change in the year ahead
It’s been a wild year for the M&A market, with plenty of headwinds forcing dealmakers to pivot, get creative, and test their patience.
Through the churning M&A tides, however, the aerospace and defense (A&D) sector has surfaced as an anchor in the storm. Record-setting government budgets have the defense sector front-and-center for A&D-focused acquirers, while SpaceX’s mega-IPO earlier this year has garnered new excitement for the space arena.
Even so, not even the A&D sector can avoid impact from market disruptions and uncertainty.
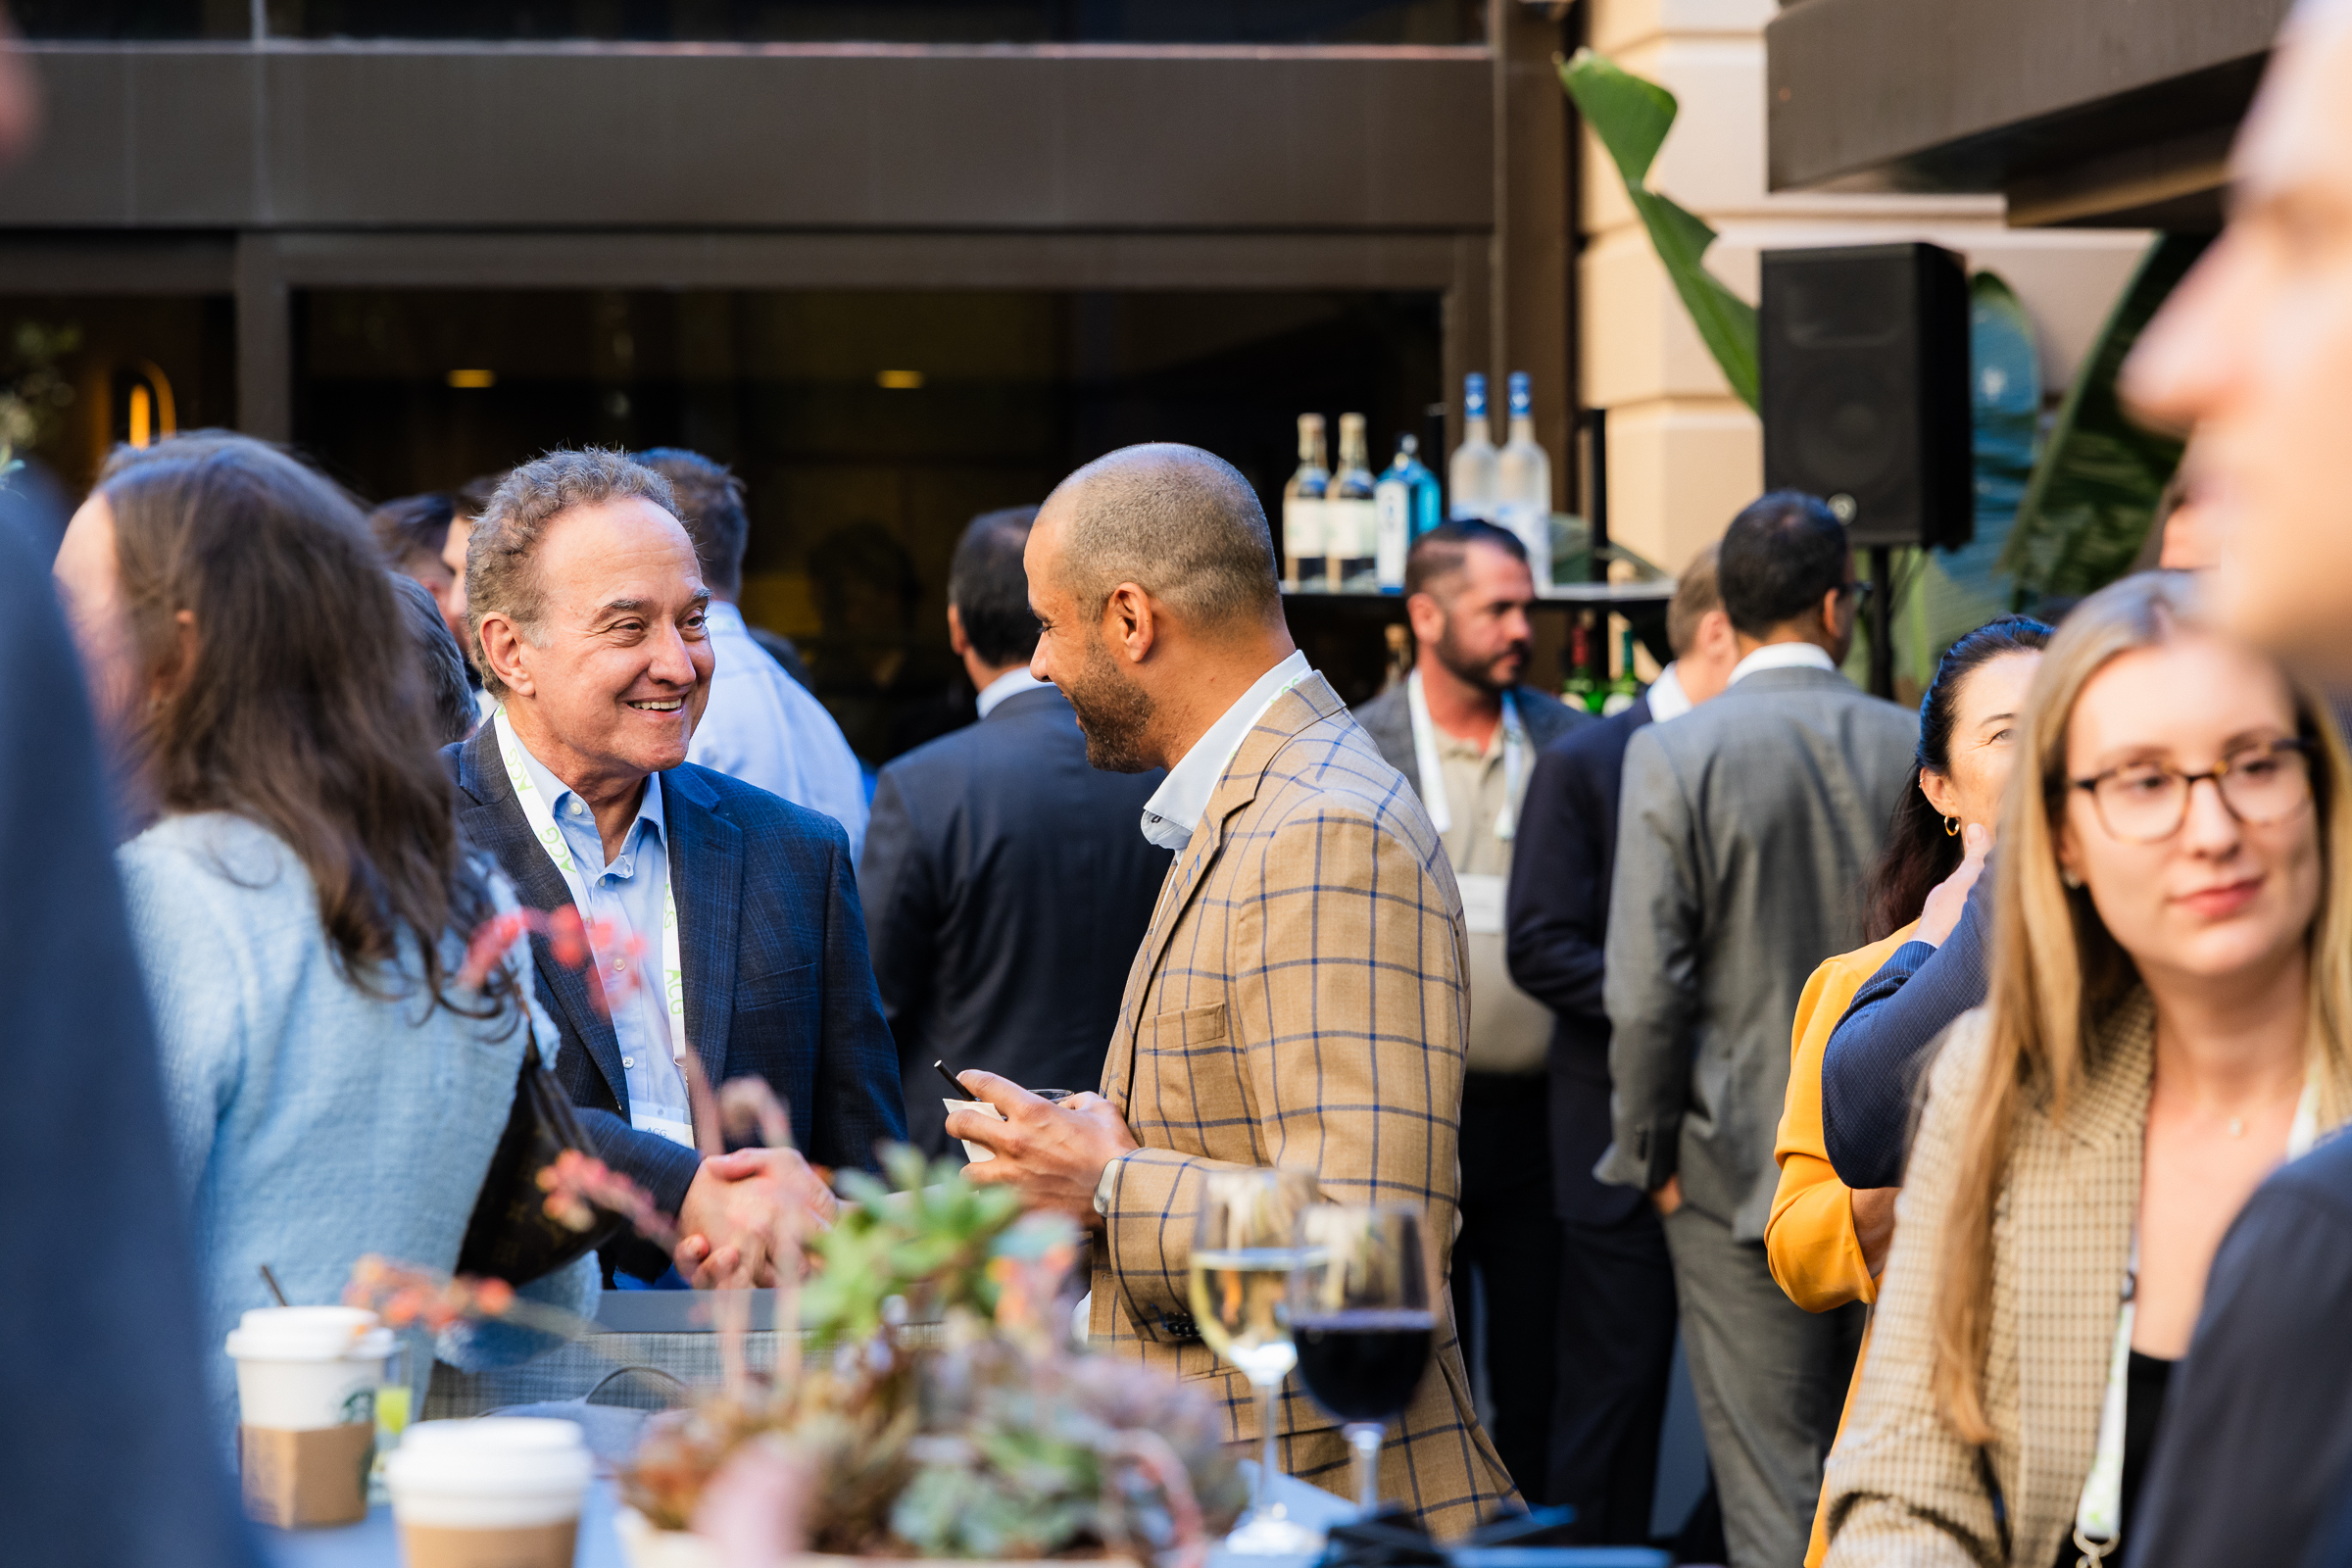
Experts gathered Oct. 14-15 in Los Angeles for ACG’s Aerospace & Defense Middle Market Leadership Forum to unpack the industry’s strengths, and potential weak spots, for nearly 300 attendees. Amid an estimated 700 meetings held between dealmakers at the event, guests were offered opportunities to listen to expert discussions that reflected on an active year for A&D investing, and considered how the sector is bracing for more change in the year ahead.
Event Recap
WHAT: ACG Aerospace & Defense Middle Market Leadership Forum
WHEN: Oct. 14-15, 2026
WHERE: Los Angeles
THE TAKEAWAY: Dealmakers active in the A&D space reflected on an active year and shared insights into where M&A activity may find its steadiest footing into 2027.
Preparing for Public Liftoff
A&D found itself in the headlines quite a bit this year, with the U.S. Department of Defense’s $1.5 trillion defense budget, SpaceX’s June IPO, and NASA’s announcement of plans for another lunar visit.
With so much excitement generated in the A&D space, IPO expectations for the market were high coming into 2026, as experts told event attendees across several panels, including the event’s “A&D IPOs Prepare for Takeoff” discussion. Yet by the second half of the year, investor appetite for risk had waned, the cost of capital increased, and by September—a month in which only two of the 13 anticipated IPOs successfully went through—it was clear that 2026 may not be the blockbuster year for IPOs it had once appeared to be.
The result, speakers said, is a backlog of A&D IPOs now “stuck in limbo” as they wait for their window for equity issuance to open back up. Private companies in the industry—including those looking to go public as well as others seeking private capital—will have to sharpen their investor pitches, bring on stellar management teams, and tell a story of operational readiness that investors can use to justify selective investments.
While it generated plenty of hype for not only A&D investment, but the public markets overall, the SpaceX IPO was a “one of one” event, one speaker noted. Downward pressure from September’s interest rate hike has weighed particularly heavy on the space sector, though one event speaker pointed to strong interest in the market, particularly when it comes to ground control of space assets like satellites and rocket launches. And when it comes to valuation? “The sky is the limit,” he said.
Other promising signals for A&D IPOs can be found within commercial aerospace, which has emerged as an attractive target for public equity investors as the sector continues rebounding from a COVID slump. Defense and defense technology, meanwhile, has proven to be the strongest in terms of private equity and venture capitalist exits to the public markets, driven by geopolitical conflict and the nation’s defense buildout.
Brightening Signals
Even with September’s IPO hiccup, the A&D market remains among the most resilient for investors across the private and public sectors.
That doesn’t mean the industry is insulated from market disruptions and uncertainties, however. During the event’s “Investment Banker Panel: A&D Deal Insights from the Front Lines” discussion, experts agreed that interest rates and an impending change in presidential administrations remain influential for investors.
The A&D arena also remains vulnerable to the dealmaking landscape’s widespread exit challenges as holding periods increasingly exceed five, six, and even seven years. As a result, A&D assets are beginning to be churned over into continuation vehicles, or for some private equity sponsors, leading firms to become “zombie” funds who continue to hold assets without new fundraising or acquisitions.
Even so, one panelist said, transaction activity and valuation levels remain robust for the strongest investment targets, particularly “A” assets that continue to attract investor appetite from strategics and private equity firms. Those top performers are also optimistic about their IPO potential.
Commercial maintenance, repair, and operations (MRO), as well as defense technology and electronics, will continue to see active M&A markets in the year ahead, several panelists predicted, noting many deals are now trading beyond 10-12x EBITDA, particularly for above-average assets (one panelist said he’s seeing defense tech valuations often reach 20x EBITDA, for example).
Speakers on this panel—and throughout the event’s programming—were largely in alignment that A&D M&A will continue its 2026 momentum into 2027, with one panelist noting that we are in the strongest deal market he’s ever seen for the industry.
Carolyn Vallejo is ACG’s senior editor.
ACG Insights is produced by the Association for Corporate Growth. To learn more about the organization and how to become a member, visit acg.org.